← All articles · October 22, 2026 · By Justin Pollard, J.D., Managing Broker & CEO, Realty ONE Group Edge
FHA Loans in Rome, GA: 2026 Limits & 3.5% Down Guide
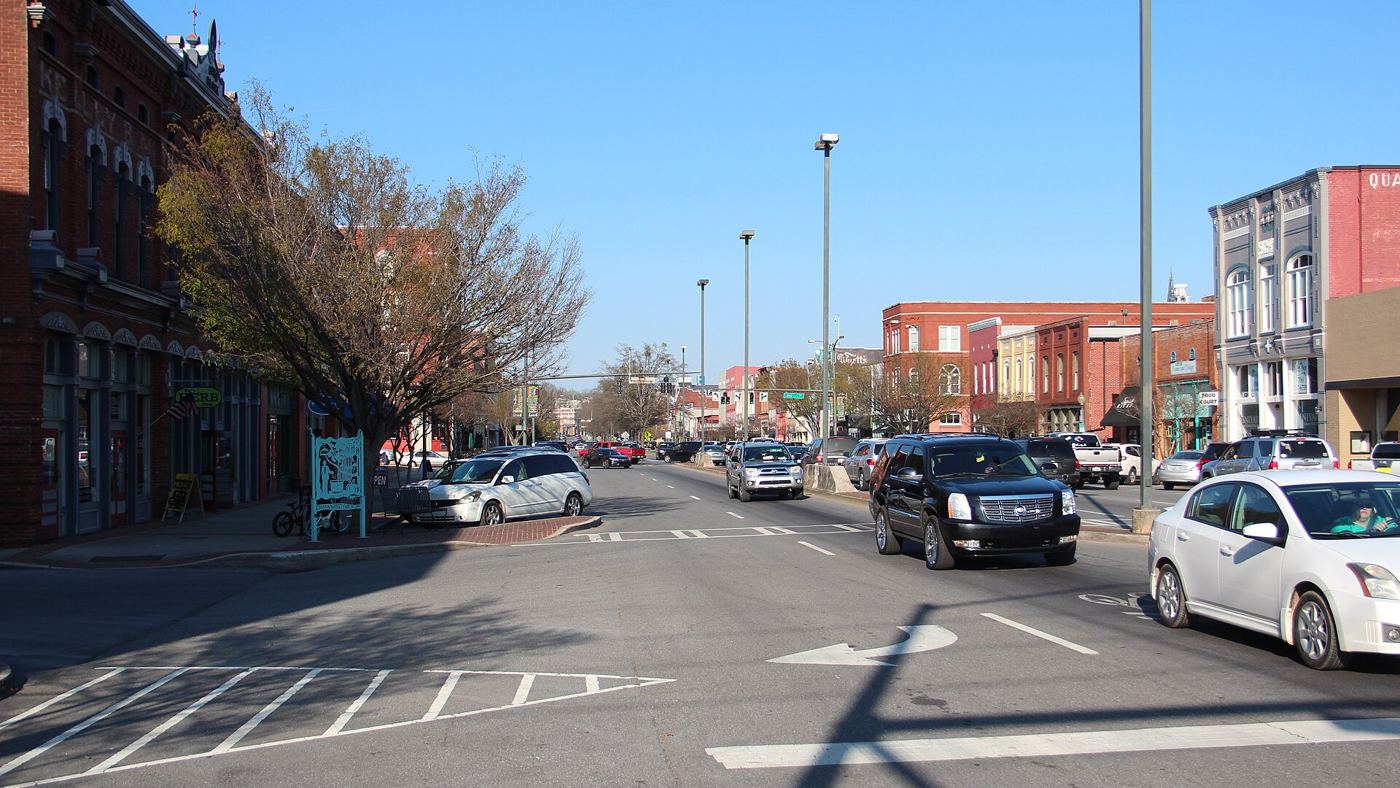

If you're buying a home in Rome, GA and don't have 20% saved, an FHA loan is one of the most common ways in the door. It allows a small down payment and is more forgiving on credit than most conventional loans. Here's how FHA financing works in Floyd County in 2026 and what it really costs.
This is general information, not lending advice. FHA rules and limits change, so confirm the details with an FHA-approved lender before you make an offer.
What Is an FHA Loan?
An FHA loan is made by a regular lender and insured by the Federal Housing Administration, part of the U.S. Department of Housing and Urban Development (HUD). That insurance lets lenders approve smaller down payments and less-than-perfect credit. You don't have to be a first-time buyer, but you do have to live in the home as your primary residence.
The 2026 FHA Loan Limit in Floyd County
FHA caps how much you can borrow, and the cap depends on the county. For 2026, Floyd County sits at HUD's national "floor," so the limits for Rome and the rest of the county are:
- Single-family home: $541,287
- Duplex: $693,050
- Triplex: $837,700
- Fourplex: $1,041,125
These limits apply to FHA case numbers assigned on or after January 1, 2026 (HUD Mortgagee Letter 2025-23). For perspective, the U.S. Census Bureau puts the median value of owner-occupied homes at $234,300 in the city of Rome and $217,900 in Floyd County (American Community Survey, 2020-2024). So for most Rome buyers, the limit won't be what holds them back.
The 2-4 unit limits are worth noticing. FHA lets you buy a duplex, triplex or fourplex as long as you live in one unit, so rent from the others can help cover the mortgage.
Credit Score and Down Payment Basics
HUD's credit rules come down to three tiers:
- 580 or higher: you can qualify with as little as 3.5% down.
- 500 to 579: you'll need at least 10% down.
- Below 500: you can't get an FHA loan.
Those are FHA's minimums; many lenders set higher cutoffs. Your down payment can come from savings or a documented gift from a family member. Sellers can also contribute up to 6% of the sales price toward your closing costs and prepaid items, but not toward your required down payment.
What FHA Mortgage Insurance Costs
The tradeoff for a small down payment is the mortgage insurance premium, or MIP, which has two parts:
- Upfront MIP: 1.75% of the base loan amount, usually rolled into the loan.
- Annual MIP: for most 30-year FHA loans with less than 5% down, 0.55% a year, paid monthly. With 5% or more down, the rate is 0.50%.
With less than 10% down, the annual MIP lasts for the life of the loan. With 10% or more down, it ends after 11 years. Many owners later refinance into a conventional loan to drop it.
Here's a simple example using Rome's median value. On a $234,300 home, 3.5% down is about $8,200, leaving a base loan of about $226,100. The upfront MIP would be about $3,957, which can be added to the loan. The annual MIP would start at roughly $104 a month and shrink slowly as you pay down the balance. That's on top of principal, interest, taxes and insurance.
The Home Has to Pass FHA's Appraisal
FHA requires the home to meet HUD's minimum property standards for safety, security and soundness. The appraisal isn't a full inspection, but the appraiser can flag issues like exposed wiring, a worn-out roof or, on homes built before 1978, chipped or peeling paint. That matters in Rome, where many neighborhoods have older homes. Required repairs usually have to be finished before closing, so talk with the seller early about who will handle them.
Making an FHA Offer Stand Out in Rome
Some sellers hesitate at "FHA" because they worry about appraisal repairs. You can ease that worry by:
- Getting fully pre-approved, not just pre-qualified, with a lender who closes FHA loans often.
- Looking at condition up front. If a house clearly needs a roof, discuss it before you sign, not after the appraisal.
- Scheduling your inspection early so you can fix problems or renegotiate while you still have time.
Is an FHA Loan Right for You?
An FHA loan can be a strong fit if you have steady income, a credit score of 580 or higher and modest savings. If your credit is strong and you can put down 5% or more, a conventional loan may cost less over time. A good lender can price both side by side.
Thinking about buying a home in Rome or anywhere in Floyd County with an FHA loan? I'd be glad to help you find homes that fit your budget and will hold up to an FHA appraisal. Call or text me at (706) 685-6478.
Justin Pollard, Pollard Property Solutions Realty ONE Group Edge | Office: 706-528-1000
Sources (for review, optional to publish): HUD Mortgagee Letter 2025-23, "2026 Nationwide Forward Mortgage Loan Limits," Dec. 11, 2025 (hud.gov); HUD News Release No. 25-145, "HUD's Federal Housing Administration Announces 2026 Loan Limits" (hud.gov); HUD, "Areas Above Floor and Below Ceiling" 2026 list (Floyd County not listed, so it is at the floor); FHA Limit Calc and Budget Sidekick, Floyd County, GA 2026 FHA limits (confirm Floyd at $541,287); HUD Mortgagee Letter 2023-05, "Reduction of FHA Annual MIP Rates" (0.55%/0.50% annual MIP, 1.75% upfront, 11-year vs. life-of-loan duration); HUD Handbook 4155.1 / 4000.1 (580 = 3.5% down, 500-579 = 10% down, below 500 ineligible; 6% interested-party contribution cap; gift funds; minimum property standards); U.S. Census Bureau QuickFacts, Rome city and Floyd County, GA, median value of owner-occupied housing units, ACS 2020-2024. Example math is my own calculation from those figures.
Justin Pollard, J.D. · GA license #374145 · Realty ONE Group Edge, brokerage license #79426 · Office (706) 528-1000